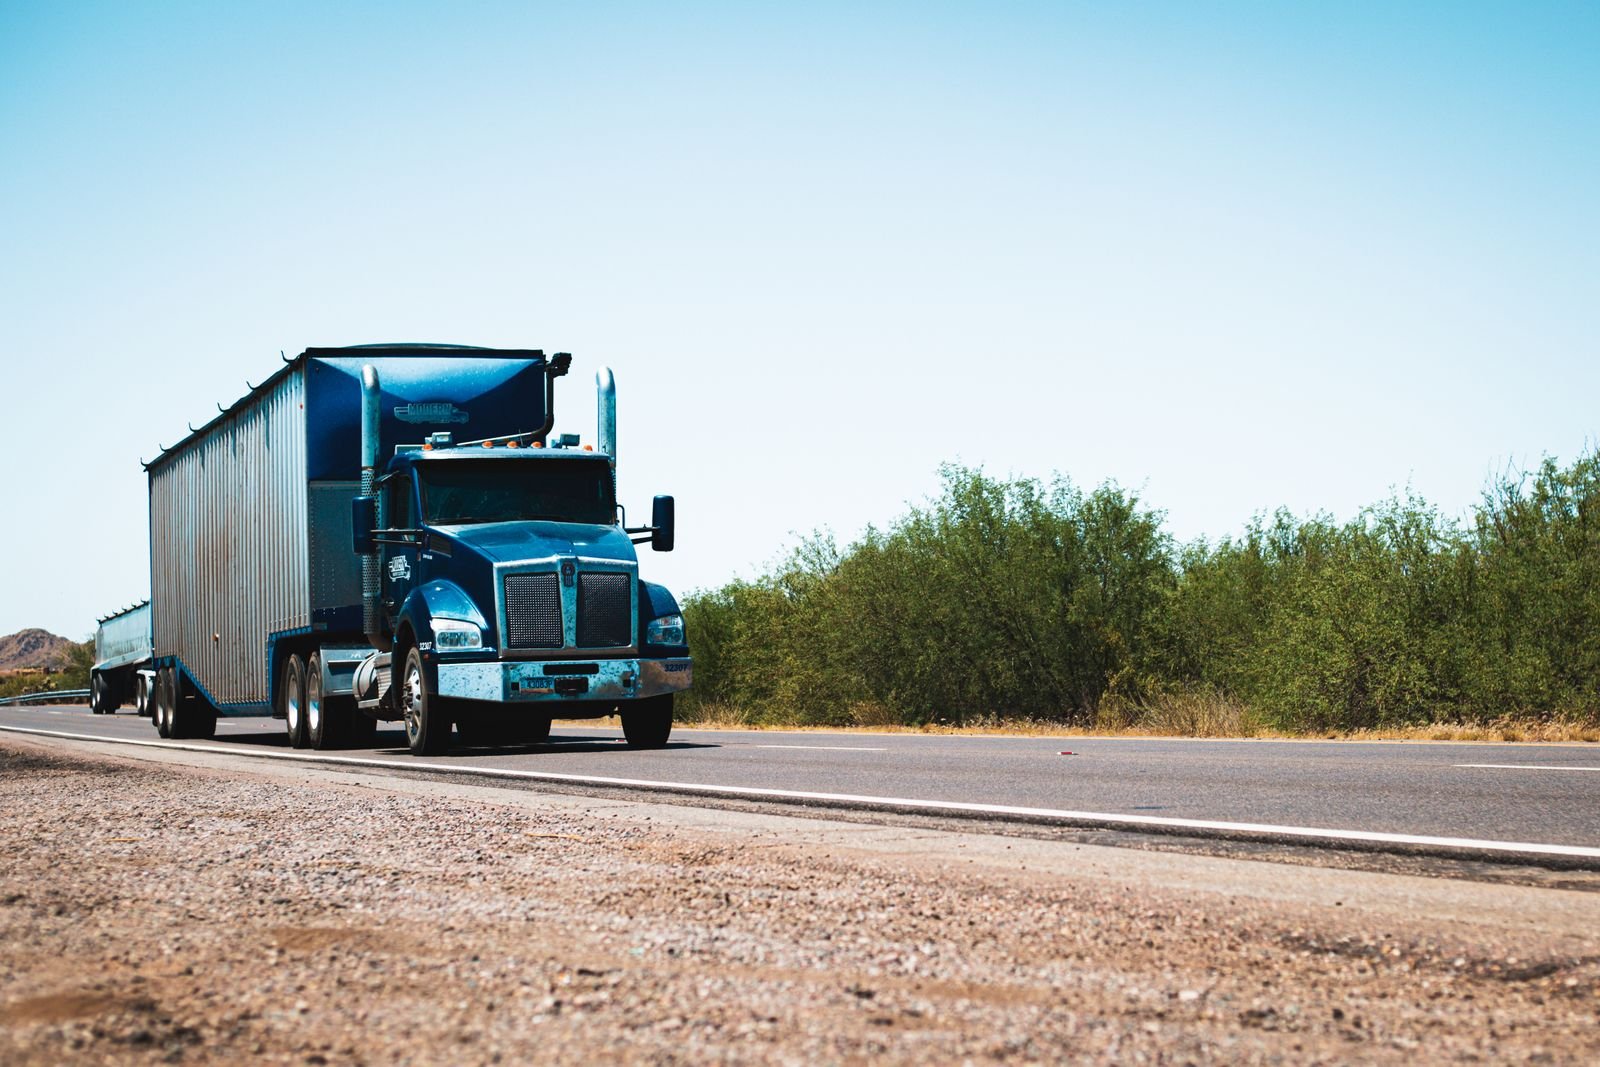
A for-hire truck with a gross vehicle weight rating of 10,001 pounds or more, hauling ordinary freight across a state line, has to carry at least $750,000 in public liability under 49 CFR 387.9. The date column on that table reads January 1, 1985. The section has been amended since, most recently this past July, and the $750,000 line still reads exactly as it did the year the first Ford Taurus rolled out. That is the number on the MCS-90 for most of the trucks passing through Iuka on US-72, and it is worth understanding what it does and does not reach.
What the table says
The rule is a short schedule with four rows. For-hire carriers in interstate or foreign commerce hauling nonhazardous property: $750,000. For-hire or private carriers hauling oil, hazardous waste, or most listed hazardous materials: $1,000,000. For-hire or private carriers hauling specified bulk hazmat classes, such as explosives or certain poison gases: $5,000,000, and that row applies even to trucks under 10,001 pounds.
“Public liability” in this rule means bodily injury, property damage, and environmental restoration. It is not cargo coverage. It is not physical damage to the truck. A carrier can be fully compliant with Part 387 and have nothing that pays for a load of lumber that ended up in a ditch outside Burnsville.
The companion section, 49 CFR 387.7, is the enforcement half. No motor carrier operates a vehicle until the minimum is in effect. Once in effect, the policy stays in effect until terminated, and cancellation by either side takes 35 days’ written notice. The endorsement that makes a commercial auto policy satisfy this rule is the one everybody calls the MCS-90, and the 35-day clock is most of what it does.
Who the federal table does not reach
This is the part owners get wrong in both directions.
A private carrier hauling its own nonhazardous goods, a lumber yard delivering with its own truck or a farm-supply store running its own route, is not in the first row. The federal floor for that operation, hauling nonhazardous freight, is not in this table at all.
A truck that never crosses a state line is under Mississippi’s rules for intrastate carriers, not this schedule, unless it’s hauling hazmat in bulk. Plenty of dump trucks and log trucks around Tishomingo County fall in that category.
And the $750,000 floor was written for 1985 dollars. A serious injury claim today can run past it without much effort, which is one reason the number has been argued over in Washington for a decade. We’re not going to tell anybody what limit to carry. We will say that most for-hire operators we see around here carry more than the floor, and the reason is usually a contract rather than a regulation.
The contract is where the real number lives
Brokers and shippers write their own insurance requirements into carrier agreements, and those routinely ask for more liability than the federal minimum, plus cargo coverage the federal rule never mentions. A carrier that meets Part 387 and shows up with a certificate that doesn’t meet the broker’s packet doesn’t get the load. That’s the practical floor for most for-hire operators, and it is set by whoever is paying for the haul.
Which means the document to read is not the regulation. It’s the carrier agreement, side by side with the commercial auto policy and its endorsements, to see whether the limits, the cargo form, and the additional-insured wording line up with what the contract demands.
Reading your own
Whether a given truck is for-hire or private, interstate or intrastate, and what it hauls, decides which row of that table applies, if any. Whether the policy in the cab satisfies it is decided by the endorsement page. Whether it satisfies the broker is decided by the contract. Three documents, three answers, none of them settled by a rule of thumb.
If you run trucks out of Tishomingo, Alcorn, or Prentiss County and nobody has laid the carrier agreement next to the policy, see our business insurance page, stop by the Iuka office, or call or text 662-454-7831 and we’ll go through both with the regulation open.
This article is general information about how coverage typically works, not advice about your specific situation. Your policy is the contract, and it’s the only thing that says what you have. If you’d like someone to read it with you, that’s what we’re here for.